HMO Licensing in 2026: A Landlord's Complete Guide
Letting to multiple households can boost yields — but the rules are strict. Here's how HMO licensing works in 2026 and what every landlord must comply with.
Drafted with AI assistance, edited and fact-checked by the TrueDeed team. No named specialist has signed this off yet.
General information, not legal, financial, tax or surveying advice. Check the primary sources linked in the article, and take advice from a qualified professional for your own situation.
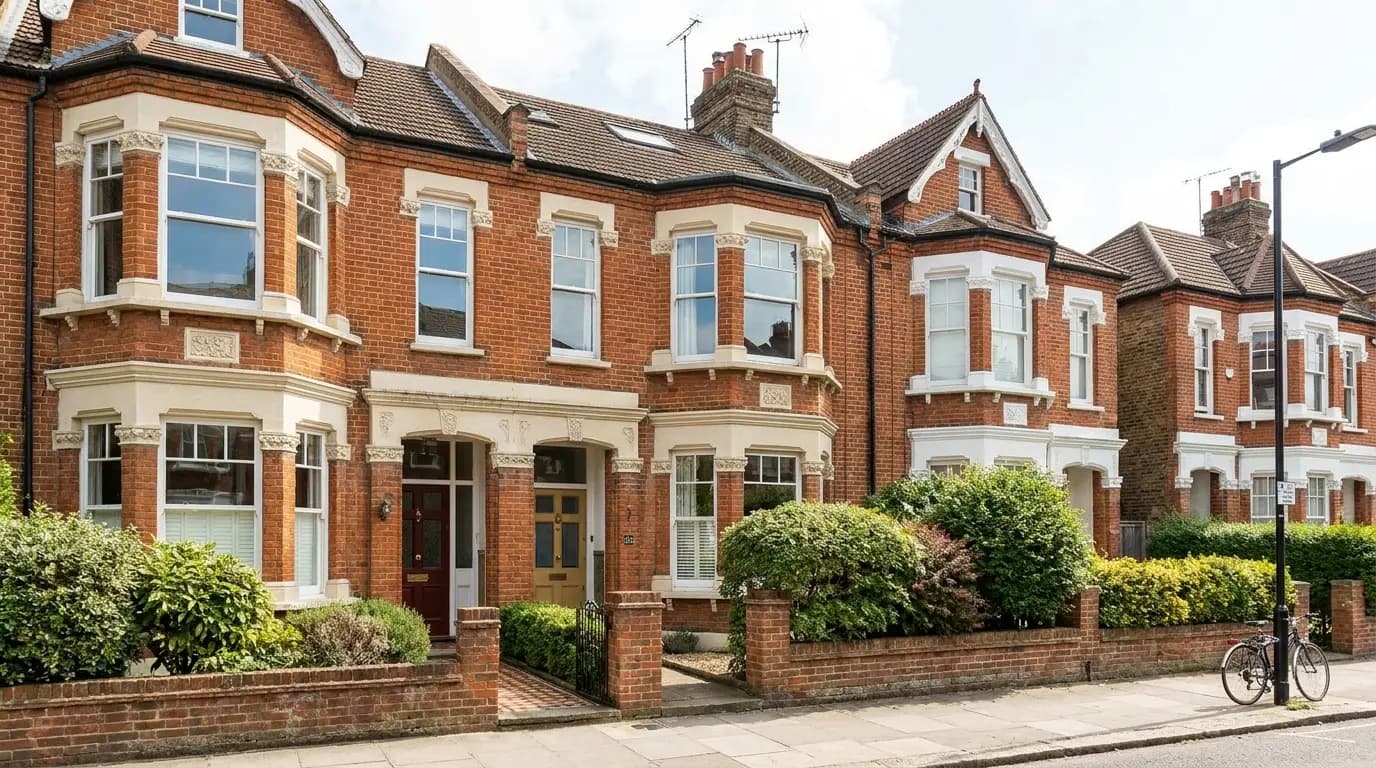
Houses in multiple occupation can deliver some of the strongest rental yields available to landlords — but they come with the heaviest regulation, and HMO licensing is where many otherwise careful landlords slip up. Letting a property to several unrelated tenants triggers a web of legal duties around safety, space and management, and getting it wrong carries serious financial penalties. This guide explains when you need a licence, how the houses in multiple occupation rules work in 2026, and what compliance actually involves.
What counts as an HMO?
Broadly, a property is a house in multiple occupation when at least three tenants live there forming more than one household, and they share facilities such as a bathroom or kitchen. A household generally means a single person or members of the same family living together. A typical example is a house let room by room to a group of unrelated working professionals or students who share the kitchen and bathroom.
“The definitions can be subtle, and a property can become an HMO almost by accident as tenancies change. If you let to sharers, always check your specific arrangement against the rules — and your council's policy — rather than assuming.”
When do you need an HMO licence?
There are three layers of licensing to be aware of, and which apply depends on the property and the local authority.
Mandatory licensing
GOV.UK says a property is an HMO if at least three tenants live there, forming more than one household, and they share a toilet, bathroom or kitchen. A household is one person or members of the same family. The Licensing of Houses in Multiple Occupation (Prescribed Description) (England) Order 2018 says Part 2 of the Housing Act 2004 applies to an HMO in England occupied by five or more persons living in two or more households, if it also meets the standard test, the self-contained flat test (but not a purpose-built flat in a block of three or more self-contained flats), or the converted building test. The Order does not set a minimum number of storeys. Councils can license smaller HMOs as well. Check with the council. This is not a licence decision for a particular building.
Additional and selective licensing
Beyond the mandatory scheme, individual councils can introduce their own requirements, so smaller HMOs are not automatically exempt:
- Additional licensing — a council extends HMO licensing to smaller HMOs in its area
- Selective licensing — a council requires licences for privately rented homes in a designated area, including non-HMOs
- Rules vary significantly between local authorities, and what needs a licence in one borough may not in the next
Because of this local variation, the single most important step is to check directly with the council where the property sits before you let it. Never assume the national mandatory rules are the whole picture.
Your obligations as an HMO landlord
Licensing brings a set of management and safety duties designed to keep shared homes safe and well run. These are actively enforced, and inspections do happen.
- Meet minimum room-size standards for sleeping accommodation
- Provide adequate kitchen, bathroom and washing facilities for the number of occupants
- Install and maintain working fire safety measures — alarms, fire doors and clear escape routes
- Hold a valid gas safety certificate and have electrical installations checked regularly
- Ensure the property is not overcrowded and is kept in good repair
- Display licence and management details and keep the common parts safe and clean
Thinking about whether an HMO stacks up financially? Run the numbers on your potential return before you commit.
Calculate rental yieldThe cost of getting it wrong
Operating a licensable HMO without a licence is a serious offence. The consequences are designed to outweigh any saving from cutting corners, and they can be severe.
- Substantial financial penalties or prosecution for managing an unlicensed HMO
- A rent repayment order, where tenants can reclaim rent they have paid
- Restrictions on your ability to use certain eviction procedures
- The risk of being judged unfit to hold a licence, affecting your wider portfolio
“An unlicensed HMO is not a grey area. The penalties — including orders to repay rent to your tenants — can dwarf the licence fee many times over.”
Making HMOs work for you
Done properly, HMOs can be excellent investments, often producing higher yields than a standard single let. The landlords who succeed treat compliance as part of the business model rather than an obstacle: they confirm the licensing position with the council up front, build the property to the required standards, and manage it professionally.
A practical starting checklist
- Confirm whether your property meets the HMO definition and which licences apply
- Contact the local council early to check additional or selective schemes
- Budget for licence fees, fire safety works and any room or facility upgrades
- Put robust gas, electrical and fire safety routines in place from the outset
- Model the realistic yield after all compliance costs before you buy
HMO licensing rewards landlords who do their homework. Understand the houses in multiple occupation rules, check your local authority's specific requirements, meet the standards in full, and a well-run HMO can be one of the most profitable and resilient parts of a property portfolio.
Frequently asked questions
What counts as an HMO?
GOV.UK says your property is an HMO if at least three tenants live there, forming more than one household, and they share a toilet, bathroom or kitchen. A household is a single person or members of the same family. Scotland and Northern Ireland have different rules.
When do you need an HMO licence?
GOV.UK says an HMO must have a licence if it is occupied by five or more people, and that a council can include other HMOs. The 2018 Order for England prescribes HMOs occupied by five or more persons in two or more households that meet the statutory tests. It excludes a purpose-built flat in a block of three or more self-contained flats. Check with the council.
Drafted with AI assistance, edited and fact-checked by the TrueDeed team. No named specialist has signed this off yet.